

The Reserve Bank of Malawi (RBM) is being pressed to ensure borrowers are shown the full cost of microfinance loans before signing up, amid concerns that interest rates alone may not tell the whole story.
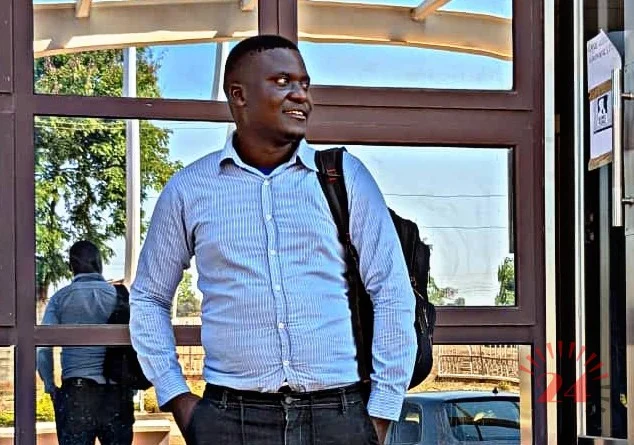
Development Economics student Tonex Mkwezalamba wants the central bank to review how microfinance institutions disclose interest, insurance, collection fees, Credit Reference Bureau (CRB) charges and other compulsory costs attached to loans.
He made the demand in a letter to the RBM Governor on 4 August 2026, asking for a review of flat-rate interest calculations, additional charges and the way the total cost of credit is presented to borrowers.
“My concern is not that microfinance institutions should not charge interest or legitimate fees. Rather, my concern is whether borrowers are given clear, comprehensive and easily understandable information about the total cost of borrowing before accepting a loan,” he said in the letter.
His demands come against the background of a K1.312 million loan carrying a stated interest rate of 3.2 percent per month over 48 months, with a monthly instalment of K82,718.
The instalments amount to about K3.97 million over the full loan period, prompting Mkwezalamba to question whether borrowers can easily understand how interest and additional charges translate into the final repayment obligation.
“A borrower seeing a rate of 3.2% per month may not necessarily appreciate how that rate translates into the total amount payable over 48 months, particularly when additional compulsory fees are included,” he said.
Mkwezalamba is therefore asking RBM to require clearer disclosure of the total cost of credit, including the method used to calculate interest, total interest payable, insurance, collection fees, CRB charges and every other compulsory cost.
He also wants borrowers to be shown an effective annual cost of borrowing and the total amount they will repay, rather than having to work out the cost from a monthly instalment and separate charges.
His proposal includes a standardised loan-cost statement showing the amount actually disbursed, nominal interest rate, calculation method, loan tenure, total interest, insurance, collection fees, CRB charges, other compulsory costs, total repayment obligation and effective annual cost.
Mkwezalamba is further asking RBM to strengthen loan statements so borrowers can see how much of each repayment goes towards principal, interest and other charges, as well as how their outstanding balance changes after each payment.
He wants RBM to establish whether microfinance institutions are adequately complying with existing consumer-disclosure requirements and whether those requirements are sufficient for ordinary borrowers to understand the true cost of credit.
The student says is not asking RBM to stop lenders from charging interest or legitimate fees. Instead, he wants the regulator to review disclosure of flat-rate interest, compulsory insurance, collection and administration charges, CRB-related costs, total repayment obligations and loan statements.
He also wants the central bank to consider consumer financial education and a standardised disclosure system that would allow borrowers to compare loans based on their actual cost.
In the loan example submitted to RBM, Mkwezalamba calculated that 3.2 percent monthly interest on the original K1.312 million principal amounts to about K41,984 per month, or about K2.015 million over 48 months.
That would put principal and flat-rate interest at about K3.327 million, compared with total instalments of approximately K3.97 million.
He identified additional charges including about K9,840 per month for collection, K55,104 for insurance and K1,500 for CRB-related costs, which he says require a clear breakdown.
Mkwezalamba also wants an outstanding balance of approximately K2.068 million reconciled through a statement showing the original principal, principal repaid, interest charged and paid, insurance, collection fees, CRB charges, other fees, penalties or arrears and the current principal balance.
RBM acknowledged receipt of the complaint through Mark Lomosi, Senior Examiner in the Market Conduct, Financial Sector Regulation Department.
“We acknowledge receipt of your letter on the above captioned matter. We will revert accordingly,” Lomosi said.
But Mkwezalamba says he is still waiting for the substantive response.
One comment on “RBM pressed on hidden loan costs”
Leave a Reply
This is great, we need to know indeed the real cost of borrowing